

Fraudsters show up to open enrollment with stolen member details and every right answer. The voice is what gives them away.
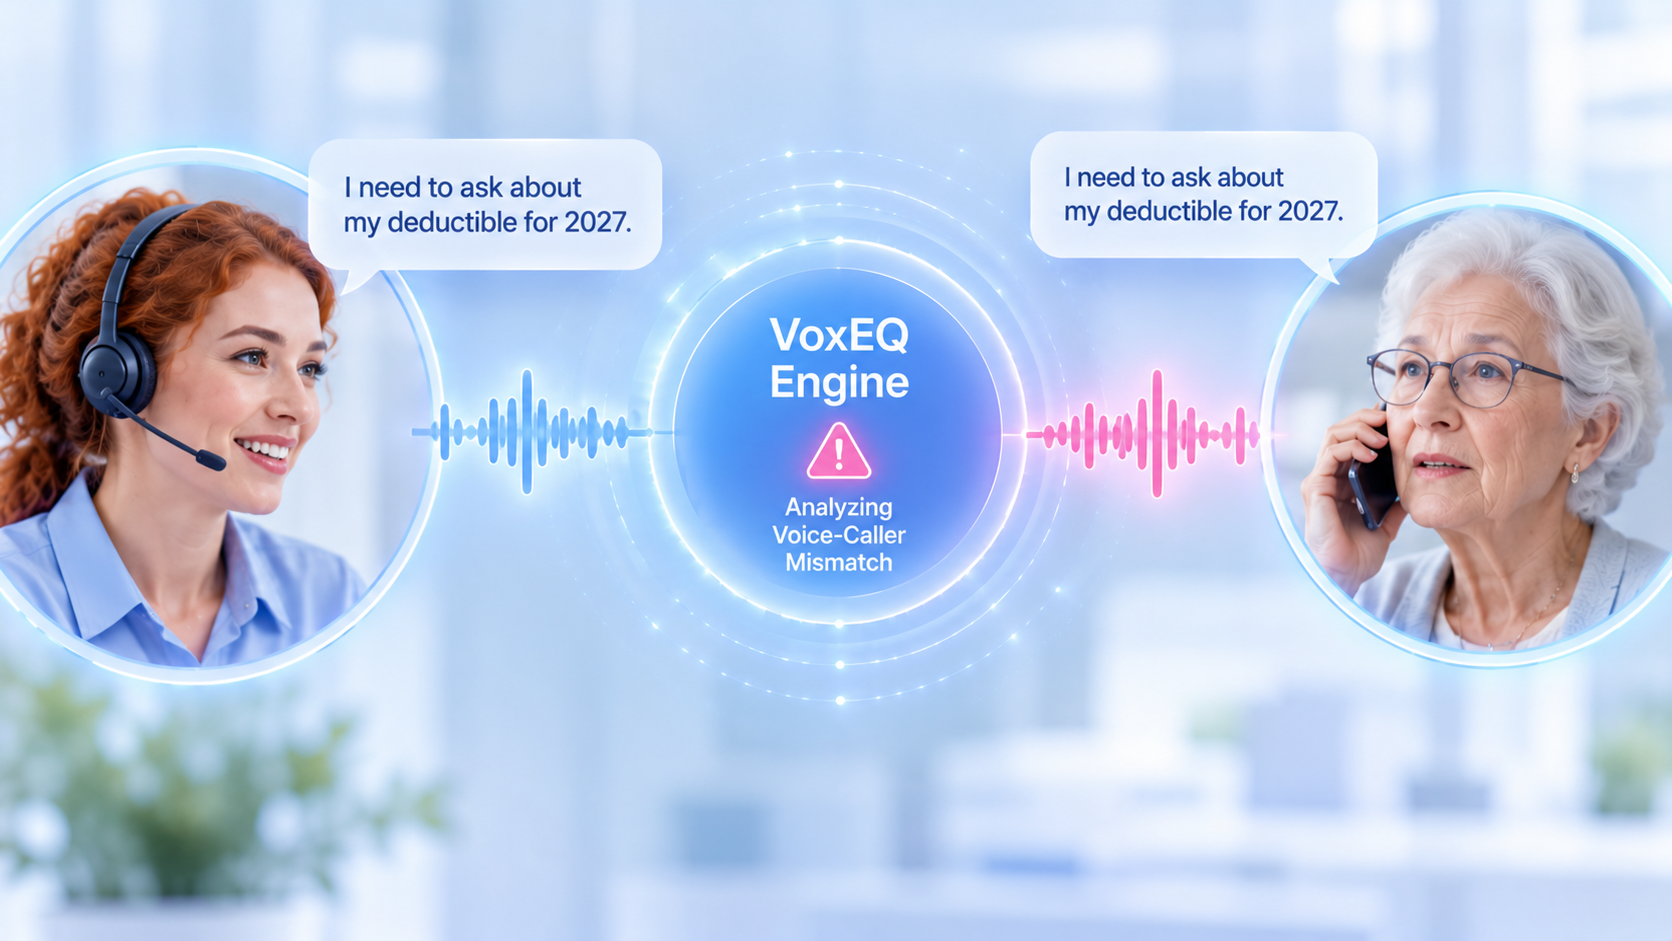
In late October, a 77-year-old Medicare Advantage member we'll call Margaret gets a call from someone claiming to be from Medicare. He's friendly, he knows her name, and he wants to make sure her coverage doesn't lapse before open enrollment closes. He just needs her to confirm her Medicare number and date of birth. She does.
That call is the scam. But it isn't where the damage happens.
Ten days later, her health plan's member services line rings. The caller has Margaret's Medicare number, her birth date and her home address. He wants to update her mailing address and order a replacement ID card before the December 7 deadline. He answers every verification question without hesitating, because Margaret already gave him the answers.
The only thing that doesn't fit is the voice. Margaret is 77. The caller sounds like a man in his thirties.
The scam call is the first call. The second one comes to you.
Three deadlines, one fraud window
Open enrollment isn't one event. Medicare's window runs from October 15 to December 7 (Kiplinger). The ACA marketplace opened November 1, and HealthCare.gov shoppers have until December 15 to get coverage that starts January 1 (NAIC). On top of that, most employers run their own benefits enrollment through November.
For a fraudster, that overlap is ideal. Call volumes are up and agents are rushed. Plan switches and address changes are routine, so a fraudulent one doesn't stand out. Every deadline is a ready-made source of urgency. And many of the people calling are seniors, the group that already loses more to fraud than any other.
It's bigger than Medicare scams
Medicare impersonation gets the headlines, but it's only one way in. The National Health Care Anti-Fraud Association conservatively estimates that fraud costs at least 3% of all U.S. health spending (NHCAA testimony via KFF), and during enrollment season a lot of it runs through the phone.
Some of it is unauthorized plan switching. CMS-confirmed complaints about people being enrolled in or moved to ACA plans without their consent rose from about 66,500 in 2023 to nearly 300,000 in 2025, according to a GAO report (Becker's Payer Issues). Some of it is account takeover: with a member ID and a birth date, a caller can change an address, order a new ID card or redirect mail-order prescriptions. And some of it is quieter, like stolen plan numbers used to bill for care that never happened, HSA reimbursements rerouted to a new bank account, or a caller fishing for claims history to set up the next scam.
Seniors carry the heaviest share. Americans 60 and older reported $7.75 billion in losses to the FBI in 2025, up 59% from the year before (HousingWire, citing the FBI IC3 2025 report).
Why the phone is where it breaks
Most phone verification comes down to a single question: does the caller know the right facts? Enrollment scams are built to collect exactly those facts, so a prepared fraudster passes as easily as the real member, and often more confidently.
Health plans have another problem banks don't. Many members call only once or twice a year, usually around enrollment, so there's little history to compare against. Older members are also the least likely to have set up voiceprint or app-based verification. Agents sometimes sense that something's off, but in the middle of a December volume spike, with a caller who has every answer, that feeling rarely stops a request.
A signal the scammer can't phish
A fraudster can steal a Medicare number. They can't steal how the account holder sounds.
That's where voice intelligence comes in. VoxEQ's voice bio-signal analysis estimates three things from a few seconds of speech: birth sex, age and height. When those don't fit the account, it flags a caller-profile mismatch. On Margaret's account, the flag comes up before the address change goes through, and instead of processing the request, the agent moves to step-up verification.
For health plans, it works where other checks struggle. There's nothing to enroll in, so it covers a member's first call of the year as well as their tenth. It doesn't store voiceprints or personal data. Real members never notice it. And it doesn't replace anything; it adds one more signal to the fraud tools you already run. A mismatch isn't a verdict, just a reason to look closer.
What to tighten before the deadlines
There's about a month of open enrollment left, which is still enough time to make a difference. Start with the requests fraudsters want most: address changes, ID card reissues, plan switches, payment updates, and new dependents or beneficiaries. Treat deadline pressure as a signal worth noticing, not proof of fraud. Add at least one check that stolen facts can't pass. Give agents a clear step-up path, so a doubt doesn't turn into a judgment call under queue pressure. And route senior members to agents trained for these calls, since they're both the most targeted callers and the most likely to need extra time.